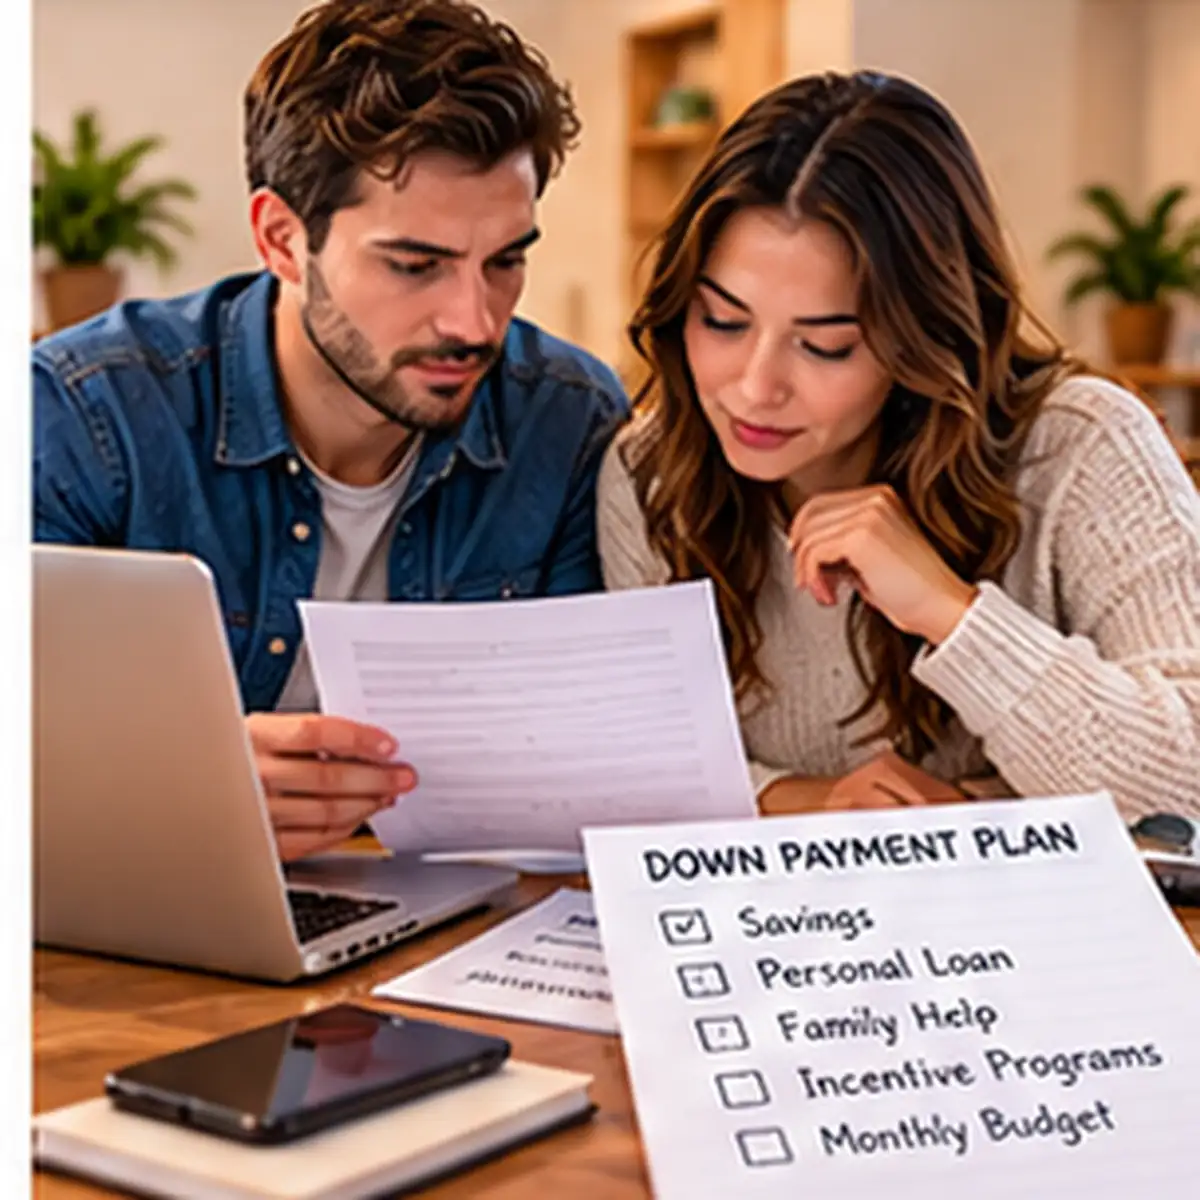
 Buying a home is one of the largest financial decisions many Canadians will make. Saving for a down payment can take years, particularly in communities where housing prices have increased substantially. Some prospective buyers investigate personal loan services in Alberta while considering ways to reach their savings goals. However, using borrowed funds toward a home down payment can create serious complications with mortgage approval, lender requirements, and long-term affordability.
Understanding the Purpose of a Down Payment
A down payment is the amount a buyer contributes toward the purchase price of a property.
The remaining amount is typically financed through a mortgage, subject to lender approval.
Canadian mortgage down payment requirements depend on factors including the purchase price, mortgage type, and applicable insurance rules.
A down payment demonstrates that a buyer has financial resources available toward the purchase.
It also influences the amount borrowed through the mortgage and may affect other financing costs.
Before making an offer, prospective buyers should understand the requirements that apply to their intended purchase.
Why Borrowing a Down Payment Can Be Problematic
Mortgage lenders generally examine where a buyer’s down payment funds originated.
Funds from savings, eligible investments, or an acceptable gift may be treated differently from money obtained through an unsecured loan.
A personal loan used toward a down payment creates an additional repayment obligation.
That obligation can affect the borrower’s debt-service calculations and mortgage eligibility.
Some mortgage programs restrict or prohibit borrowed down payments, while particular programs may permit certain borrowing arrangements under specific conditions.
Buyers should never assume that a personal loan will be accepted as a down payment source.
Discussing the situation with a qualified mortgage professional before borrowing is essential.
How Additional Debt Affects Mortgage Qualification
When evaluating mortgage applications, lenders assess income, existing debts, housing costs, and other financial commitments.
A new personal loan can increase the applicant’s monthly debt obligations.
This may reduce the mortgage amount for which the person qualifies.
For example, someone who borrows money to increase available down payment funds may simultaneously increase the debt payments considered during mortgage underwriting.
The result could be less borrowing capacity rather than improved affordability.
Applicants should disclose liabilities accurately and follow the lender’s documentation requirements.
Exploring Canadian Homebuyer Savings Programs
Canadians preparing to purchase their first qualifying home may benefit from investigating registered savings programs.
The First Home Savings Account allows eligible individuals to save for a qualifying first home with specific tax advantages.
The Home Buyers’ Plan may also permit eligible buyers to withdraw amounts from their registered retirement savings plans under applicable conditions.
These programs have contribution limits, eligibility rules, and other requirements.
Prospective buyers should review current program details and consider professional financial or tax guidance where appropriate.
Planning through eligible savings programs may be more suitable than taking on expensive debt.
Understanding Gifted Down Payments
Some homebuyers receive financial assistance from family members.
Mortgage lenders may accept qualifying gifted funds under specific conditions.
Documentation is generally required, and lenders may need confirmation that the money is a genuine gift rather than a loan requiring repayment.
Different lending institutions have different policies.
Buyers should avoid informal arrangements that misrepresent borrowed money as a gift.
Accurate documentation is important throughout the mortgage approval process.
Budgeting Beyond the Down Payment
A home purchase involves additional expenses beyond the initial contribution.
Legal fees, property inspections, moving expenses, insurance, adjustments, and other closing costs may need to be paid.
After purchasing the property, homeowners must also account for utilities, maintenance, property taxes, and unexpected repairs.
Using every available dollar toward the down payment can leave little financial flexibility.
A realistic homeownership plan should include both purchase costs and ongoing obligations.
Building Savings More Effectively
Prospective buyers can begin by setting a realistic target based on the properties they are considering.
Reviewing household spending may identify opportunities for additional savings.
Automatic transfers into a dedicated account can make progress more consistent.
A longer savings timeline may also reduce the temptation to rely on high-cost credit.
Making an Informed Homebuying Decision
Borrowing to increase a down payment should never be undertaken without understanding mortgage lender rules and the consequences of additional debt.
An experienced mortgage professional can explain which sources of funds may be acceptable for a particular application.
For many Canadians, building savings and reducing existing debt may improve mortgage readiness more effectively than obtaining another loan.
The objective is not simply to qualify for a purchase, but to maintain financial stability after becoming a homeowner.